Identifying Duplicate Patterns in Account Registers
Duplicate entries are one of the most frequent causes of ledger discrepancies when balancing personal financial books. They often occur when manual transaction logs overlap with automated file imports, or when a user double-clicks during data entry. Identifying these duplicate entries requires systematically cross-referencing amounts, posting dates, and reference numbers across your register to detect identical records entered close together.
Executing Safe Resolution and Verification Steps
Once a potential duplicate entry is flagged, it is vital to verify whether both entries have cleared your bank account or if one remains pending. If one entry is confirmed as an accidental double record, voiding or removing the redundant record restores the register balance to its correct figure. Always verify the ending balance against your official bank statement immediately following the removal of any record to ensure that no legitimate corresponding transaction was accidentally altered.
Related Articles
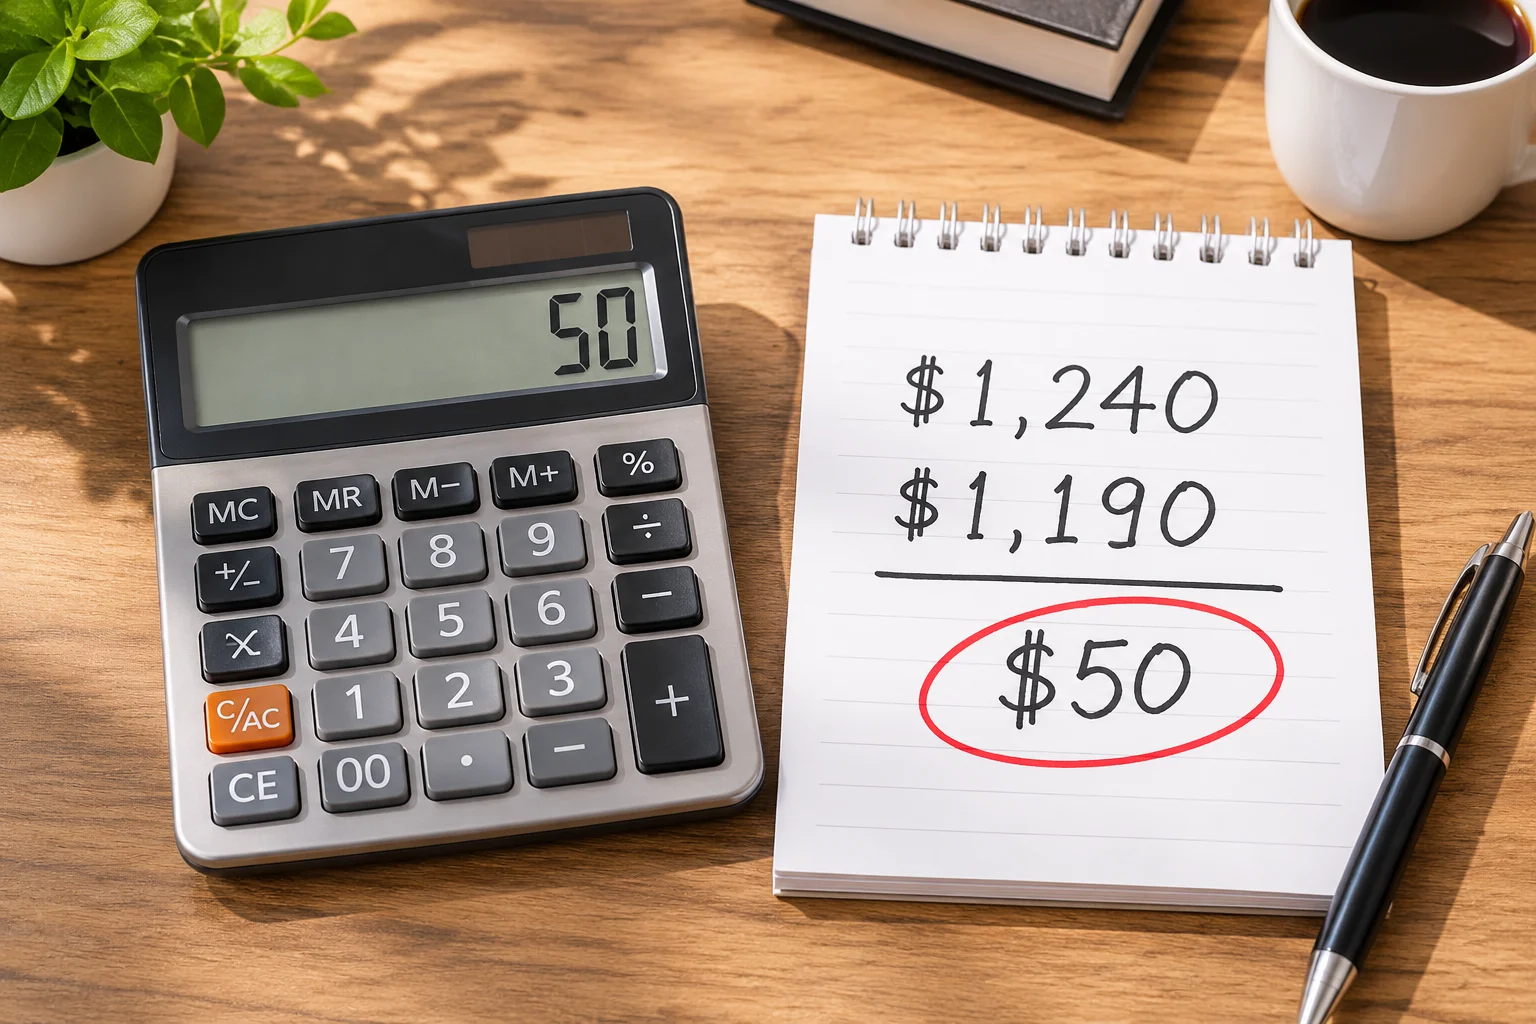
The Unmatched Payment Case Study
Detailed analysis of resolving $50 discrepancies between bank registers and ledger statements.
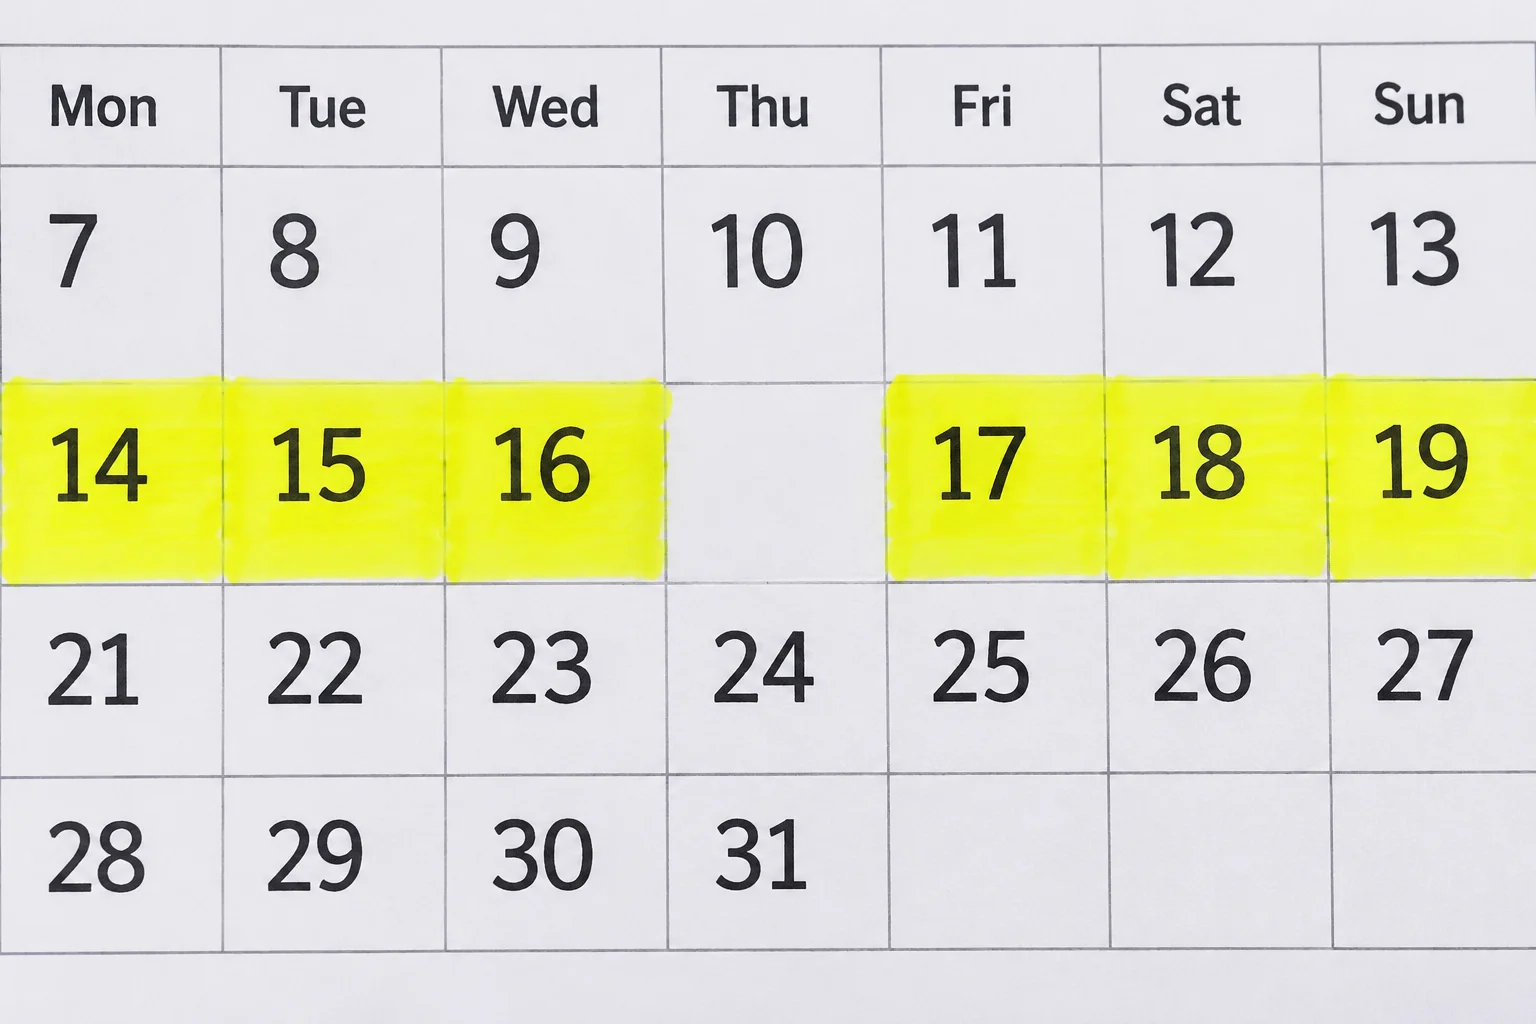
Identifying Missing Statement Dates
Learn how to detect missing date windows and fill sequence gaps in ledger statements.
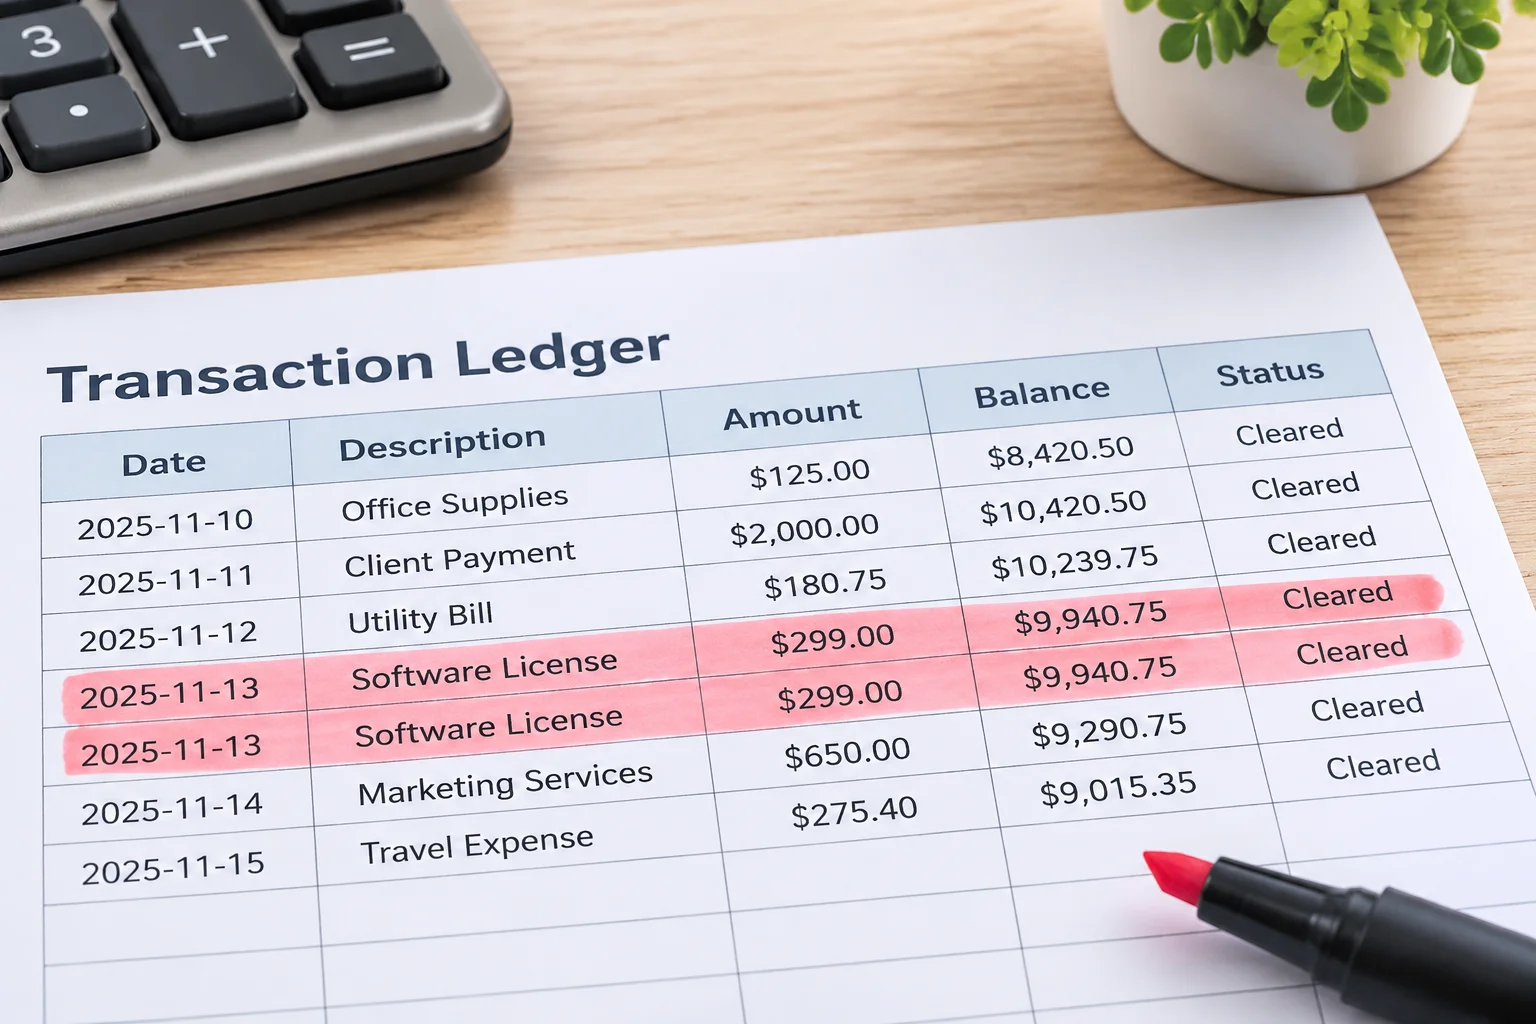
The Duplicate Payment Record
Practical techniques for preventing automated bank feeds from generating double entry records.